India Bank Credit Is Up 19 Percent, and the Biggest Single Contributor Is Lending to NBFCs
Published: September 19, 2026
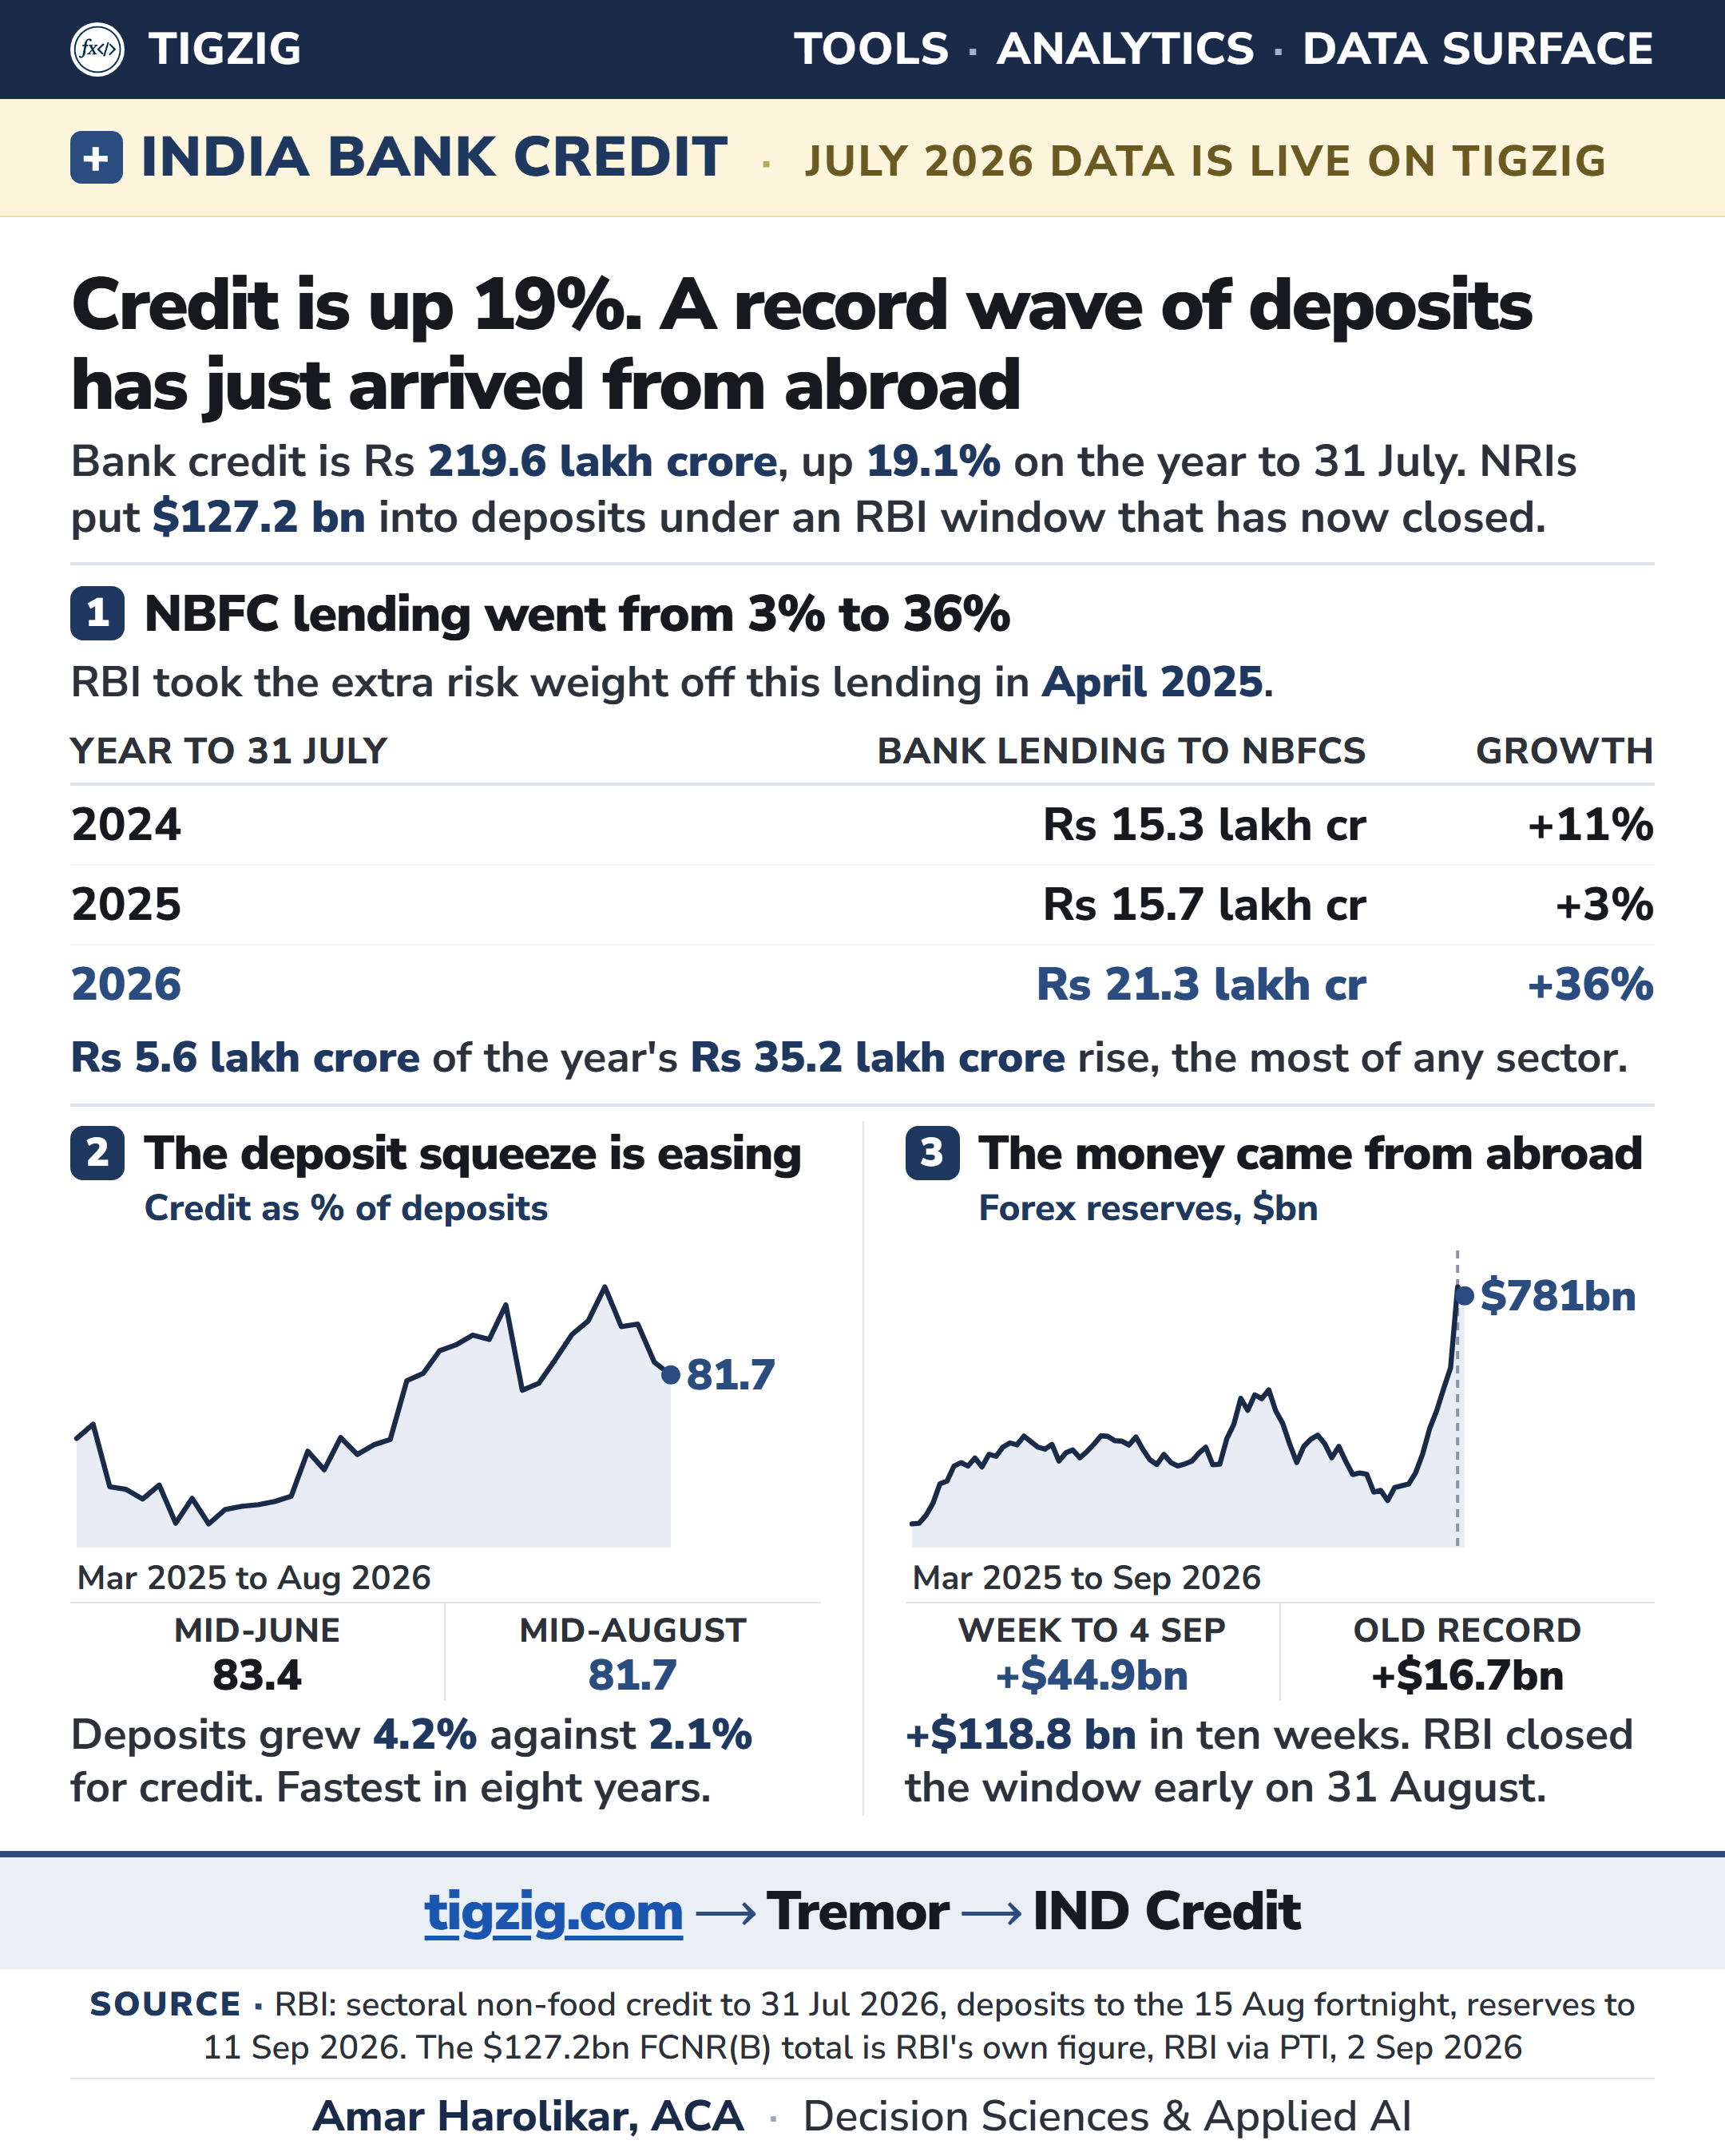
India's July 2026 sectoral credit data is live on Tigzig TREMOR. Non-food bank credit is Rs 219.6 lakh crore, up 19.1 percent over the year, and the single biggest contributor to that growth is bank lending to NBFCs.
Lending to NBFCs is Rs 21.3 lakh crore, up 35.7 percent, and it accounts for Rs 5.6 lakh crore of the Rs 35.2 lakh crore the whole book added over the year. A year ago that same growth rate was 3 percent.
What changed in between is a rule. RBI put an extra 25 percentage points of risk weight on bank lending to NBFCs in November 2023, and took it off effective April 2025. Growth went 11 percent, then 3 percent, then 36 percent across the three Julys.
So a good part of what reads as a broad credit boom is banks funding non-banks, and that exposure tells you whether the NBFC is paying the bank, and nothing about the borrowers underneath.
On gold, one caution. The Rs 5.5 lakh crore of gold jewellery loans here is banks only. ICRA puts the organised book, banks and NBFCs together, at about Rs 18 lakh crore as of March 2026. More on that below.
Where to get the data
For you, the interactive tool is at tigzig.com/tremor, then IND Credit.
For your AI agent, have it pull the data over MCP or the API, including the full database download. Point it at api.tigzig.com/v1/openapi.json and it knows what to do.
The API and MCP docs are at tigzig.com/apis/tremor.
More on the gold number
The sectoral release only shows you one part of it.
Loans against gold jewellery are up 88 percent over the year to Rs 5.5 lakh crore, and that line is banks only, and inside banks it is the retail slice. Gold backed lending that banks book under agriculture does not sit in it, and NBFC gold loans are not in this release at all.
ICRA sized the whole organised market on 29 July 2026. Banks and NBFCs together were around Rs 18 lakh crore as of March 2026, NBFC AUM was around Rs 4 lakh crore of that, and the bank share has come down from 82 percent in March 2024 to about 78 percent. They see the total crossing Rs 30 lakh crore by March 2028.
Two things in there worth carrying. ICRA says part of the jump in bank retail gold loans is reclassification from agriculture, so the 88 percent is not all fresh lending. And on our own data gold is slowing, with month on month growth down from 7.4 percent in March to 3.1 percent in July.
ICRA press release: the 29 July 2026 release on icra.in
On the funding side
The credit deposit ratio hit an all time high of 83.38 on 15 June and has come down to 81.72 by 15 August. Deposits grew 4.22 percent between mid June and mid August against 2.14 percent for credit, which is the fastest for that window in the eight years of the fortnightly series, and M3 at 3.44 percent agrees with it.
Alongside that, there is the FCNR(B) window. RBI ran a special swap facility, banks raised 127.2 billion dollars of FCNR(B) deposits by 31 August, and RBI closed the window a month early because of the response. Forex reserves rose 44.9 billion dollars in the week to 4 September, which is the largest weekly rise in the twenty five years of that series and nearly three times the previous record of 16.7 billion.
Most of that money settled at the end of August, which is after the 15 August deposit reading, so it is not what moved the ratio between mid June and mid August. It lands in the fortnights after that.
One note on dates, because three different RBI releases are involved. The sector split is to 31 July, my deposit and credit figures are to the 15 August fortnight, and reserves are to 11 September. RBI has since published the 31 August fortnight, which takes the credit deposit ratio to roughly 80, and I will refresh the tool once it comes through.
Working on something similar? How I work covers the rates, the availability and what I take on.