France's Sovereign Debt Crisis: The Stress Is Spreading to Italy, Belgium and Greece, and France Now Pays More Than Italy
Published: October 25, 2026
France's debt crisis comes at an extremely fragile time - potential AI valuation bubble, the Iran war oil shock, many big stock markets well off their highs and strain on jobs and incomes - times like these, a small trigger could have a far bigger effect than usual.
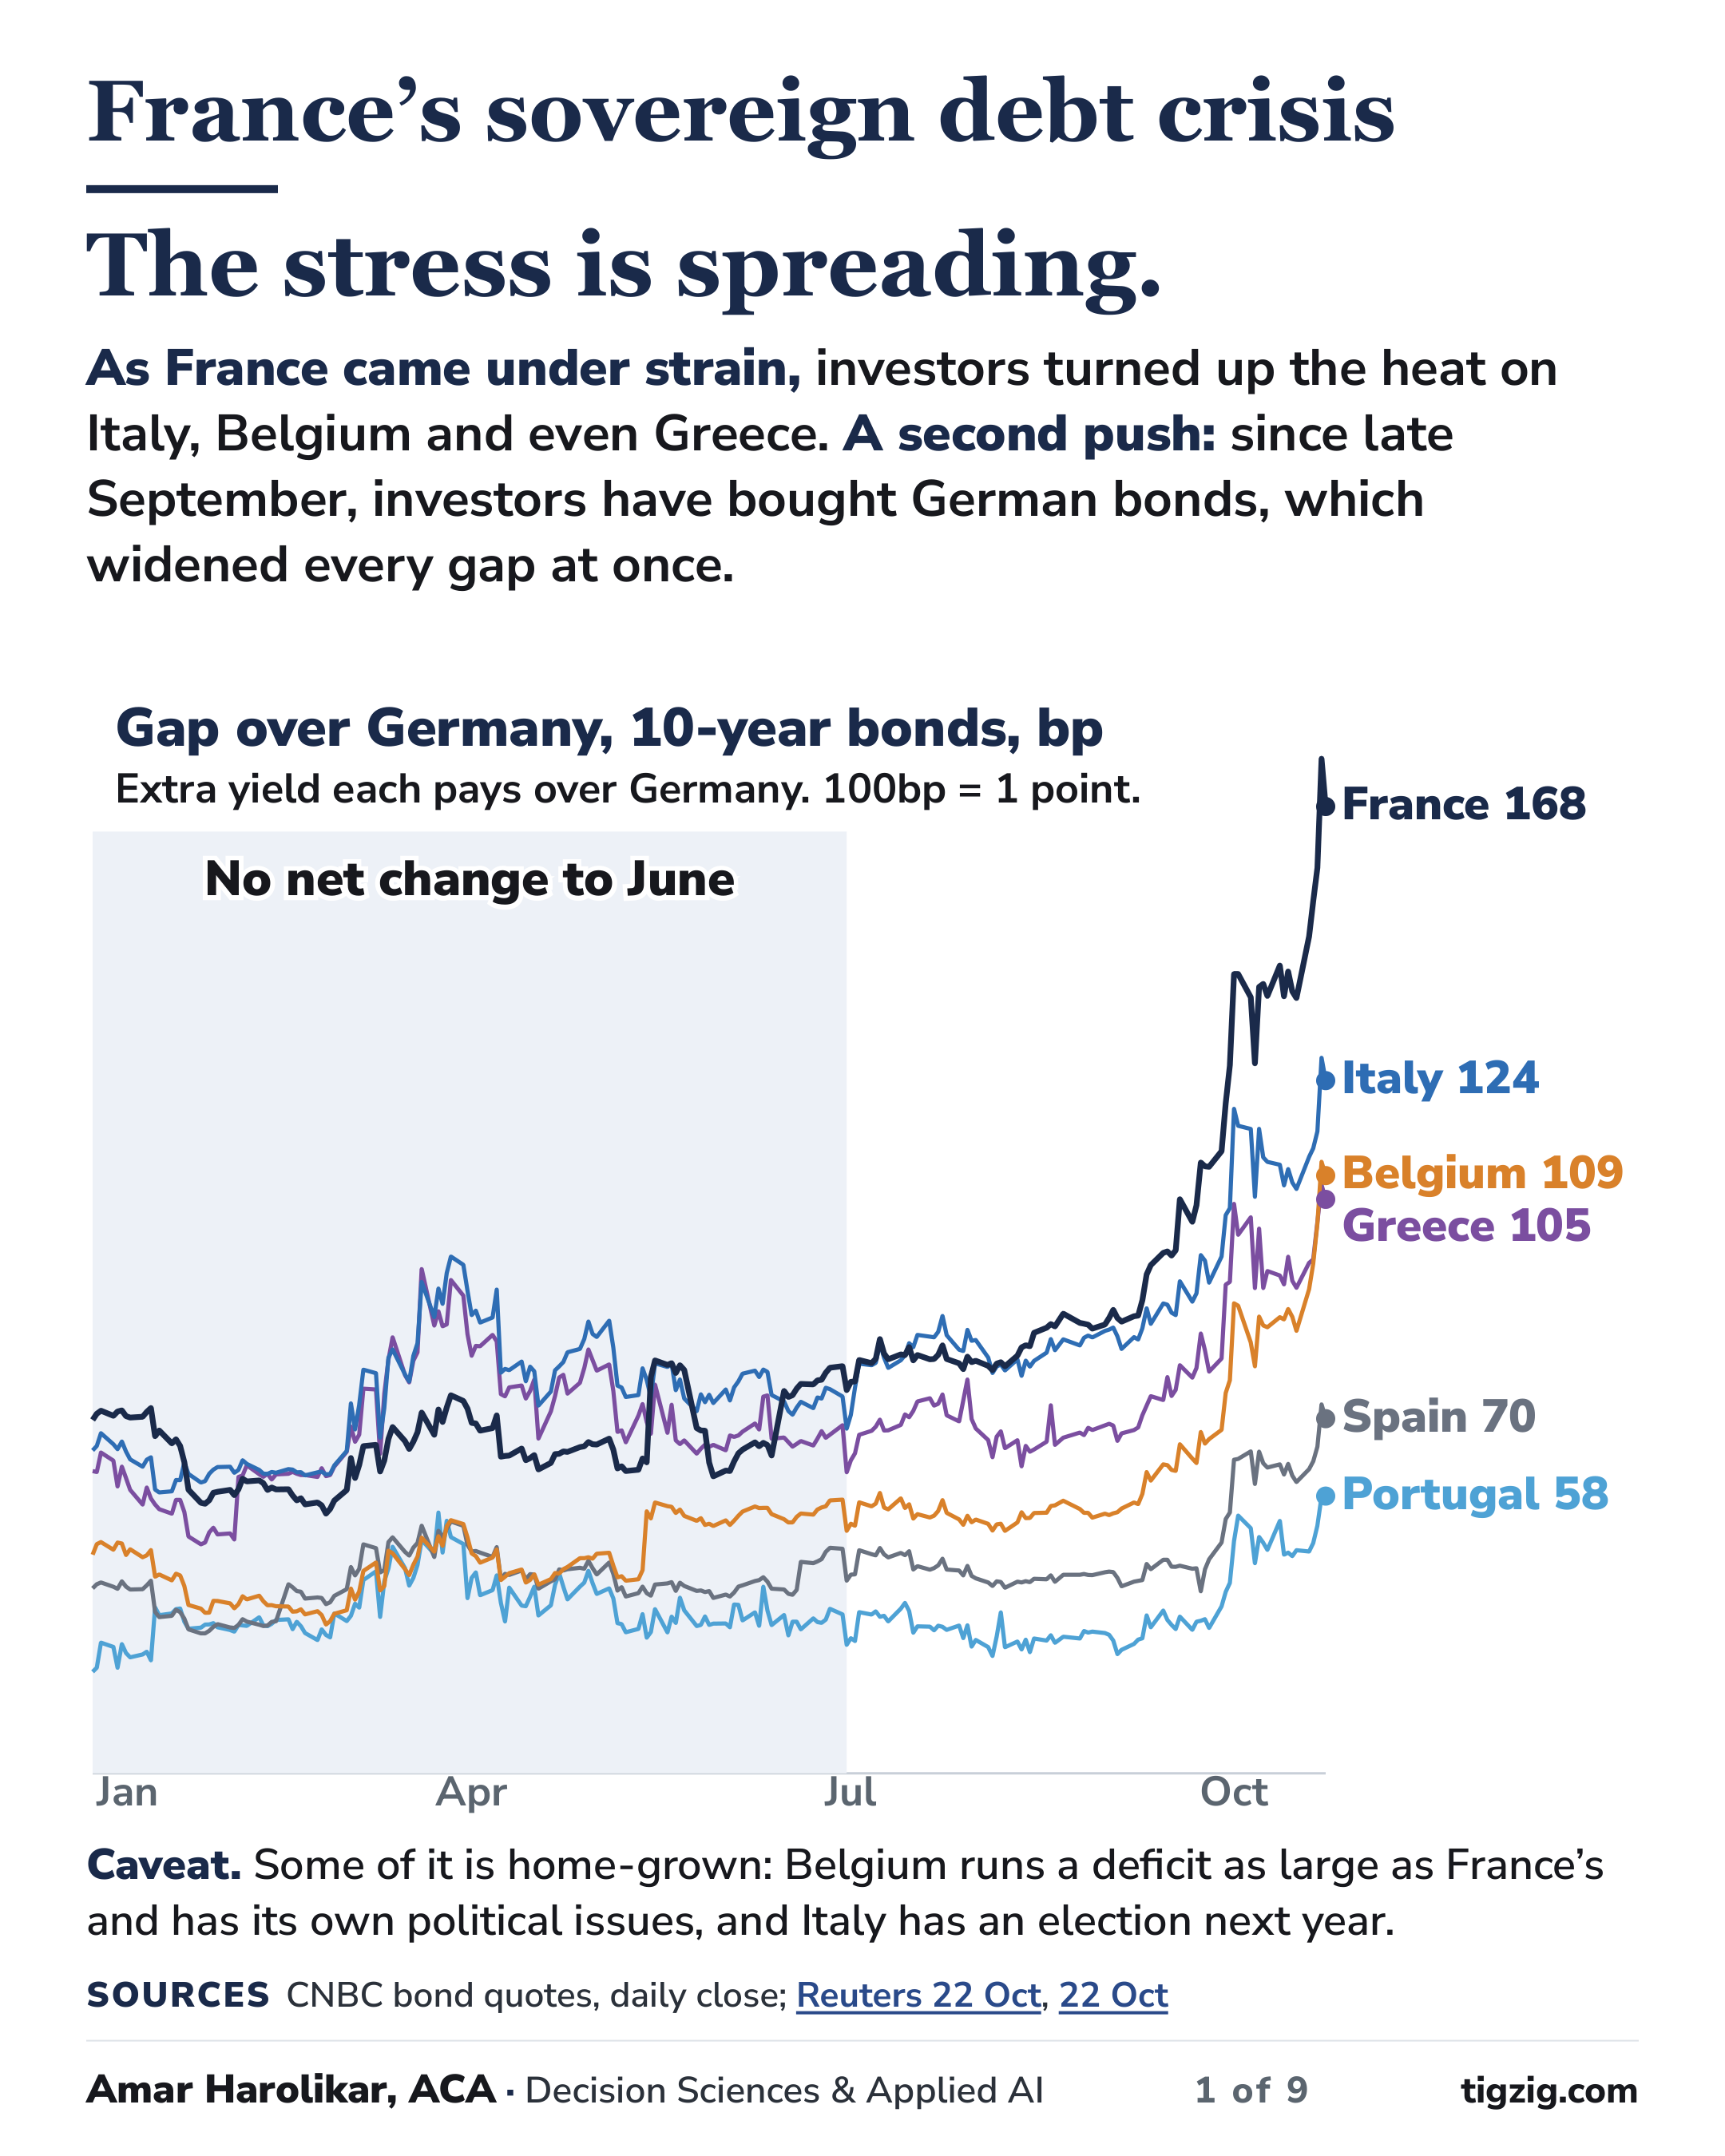
And the stress is already spreading. Italy, Belgium and Greece are paying more to borrow against Germany, and French bank shares have fallen much further than Europe's banks.
France now pays more to borrow than Italy, though its credit rating is well above Italy's.
The analysis covers who holds France's debt, the cost of insuring it against default, the ECB's options and what to watch in the next few weeks. It also has the other side: banks are stronger than in 2011-12, and most analysts CNBC spoke to see the contagion risk as limited.
More analysis at tigzig.com/analysis
A few nuances the deck could not fit
Is this contagion? Not clearly yet. The other gaps over Germany now move much more closely with France's, but some of the cause is their own. Belgium's deficit is as large as France's, and Italy has an election next year.
In October, the 10-year yields of Italy, Spain and Greece were flat or lower. Their gaps widened because German yields fell more.
Bank shares fall for many reasons. Deutsche Bank fell about as much as the Italian banks, and Paris also has weak luxury sales. Here the shares are a symptom.
Junk is below BBB-. France is A+ at S&P and Fitch, six notches above it. The level investors watch is BBB: if all three agencies cut France there after the election, investors with rating limits may have to sell (RBC BlueBay).
France first paid more than Italy on a monthly average in Dec 2025, but was below it from Mar to Jul 2026. On daily closes it has been above since 4 Aug.
Yields are CNBC daily closes to 23 Oct. Reuters' 177.7bp on 22 Oct was during the day; the close was 175bp. CDS are Investing.com monthly closes in US dollars, with France only from 2020.
Earlier analysis on a potential AI valuation bubble and various economic stress factors
Could this time be different? Past drawdowns, AI valuations and cracks across markets and the economy, 24 Oct: tigzig.com/post/drawdowns-this-time-different-oct2026
A crescendo of warnings on AI debt and returns from S&P Global, Gartner, Morgan Stanley, the IMF and the World Bank, 23 Oct: tigzig.com/post/ai-warnings-crescendo-oct2026
US housing: mortgage rates above 2007-08 and pending sales at a record low, 22 Oct: tigzig.com/post/us-housing-freeze-oct2026
US jobs, September 2026: fewer new jobs, longer searches and pay trailing prices, 4 Oct: tigzig.com/post/us-jobs-september-2026-update-oct2026
A correction in AI valuations is looking more likely, 31 Aug: tigzig.com/post/ai-valuation-correction-aug2026
Analysis of public sources, for information only. Not investment advice.
France's sovereign debt crisis
Browse the slides or download the PDF
Full Deck Content (Text Format)
Text below was extracted from the source deck. Chart visuals stay in the PDF and as slide images above the post.
Slide 1
France’s sovereign debt crisis
The stress is spreading.
As France came under strain, investors turned up the heat on Italy, Belgium and even Greece. A second push: since late September, investors have bought German bonds, which widened every gap at once.
Jan Apr Jul Oct No net change to June Gap over Germany, 10-year bonds, bp Extra yield each pays over Germany. 100bp = 1 point. France 168 Italy 124 Belgium 109 Greece 105 Spain 70 Portugal 58
Caveat. Some of it is home-grown: Belgium runs a deficit as large as France’s and has its own political issues, and Italy has an election next year.
SourcesCNBC bond quotes, daily close; Reuters 22 Oct, 22 Oct
Amar Harolikar, ACA · Decision Sciences & Applied AI1 of 9tigzig.com
Slide 2
More than half of France’s €3.46 trillion debt is held abroad. Losses on it would reach investors beyond France
France is the largest pool of euro-area government debt held outside its home country: 27% of €7.0 trillion.
Government debt, 2025, € trillion
Held abroad, % shown Held at home
France 54% €3.46T Italy 34% €3.10T Germany 51% €2.84T Spain 49% €1.70T Belgium 63% €0.69T Greece €0.36T , 71% abroad Portugal €0.28T , 47% abroad
France at home: French banks and money funds €580bn (17%), the Banque de France €572bn (17%), insurers and funds €390bn (11%).
Abroad includes investors in other euro-area countries, and the ECB. Greece’s is mostly euro-area rescue loans.
SourcesEurostat, government debt by holder, in euros and by instrument, 2025
Amar Harolikar · Decision Sciences & Applied AI2 of 9tigzig.com
Slide 3
French bank shares have fallen about twice as much as Europe’s banks since July
The bond market has spoken, and bank shares are falling too. Banks hold government bonds, so falling bond prices hit them.
Change since 31 Jul 2026, %
Banks, French dark Stock markets
Société Générale, France -25.8% BNP Paribas, France -21.3% Crédit Agricole, France -19.8% Deutsche Bank, Germany -12.4% UniCredit, Italy -11.7% Intesa Sanpaolo, Italy -10.4% European banks, Stoxx 600 -9.9% KBC, Belgium -8.7% CAC 40, Paris -8.5% FTSE MIB, Milan -6.9% BBVA, Spain -6.7% Santander, Spain -6.6% IBEX, Madrid -4.0% DAX, Frankfurt -1.7%
Reuters: in six weeks to 21 Oct, French banks fell 17% and European banks 10%; sovereign worries contributed. Caveat: not all of it is France. Since late August Deutsche Bank has fallen more than the French banks, and Paris also has weak luxury sales. Brussels (+1.7%) and Lisbon (+1.4%) rose.
SourcesYahoo Finance via tigzig.com APIs, closes to 23 Oct, banks with dividends; Reuters 21 Oct, CNBC 19 Oct
Amar Harolikar · Decision Sciences & Applied AI3 of 9tigzig.com
Slide 4
France is rated three to five notches above Italy. It now pays more to borrow
“We are deep into French crisis territory.”
Carsten Brzeski, ING, to CNBC, 23 Oct
10-year bond yield Close on 23 Oct 2026 5.02% France 4.58% Italy
Credit ratings Long-term, today
| Rating | France | Italy | Notches apart |
|---|---|---|---|
| S&P | A+ | BBB+ | 3 |
| Moody’s | Aa3 | Baa2 | 5 |
| Fitch | A+ | BBB+ | 3 |
10-year bond yields across the euro area %, close on 23 Oct 2026
France pays the most. Germany, the benchmark, pays the least.
Before interest, Italy ran a budget surplus of 0.8% of GDP in 2025. France ran a deficit of 2.9%.
France 5.02% Italy 4.58% Belgium 4.43% Greece 4.39% Spain 4.04% Portugal 3.92% Germany 3.34%
SourcesCNBC bond quotes; Eurostat; Reuters on Moody’s, S&P, Fitch, Italy; Il Sole; CNBC
Amar Harolikar · Decision Sciences & Applied AI4 of 9tigzig.com
Slide 5
The cost of insuring French debt against default has more than tripled this year
France now costs more to insure than Italy, Greece or Spain. Theirs are rising too, but are still below their 2020 Covid highs.
30 96 France ×3.2 28 73 Italy ×2.6 32 50 Greece ×1.6 19 33 Spain ×1.7 7.5 12.3 Germany ×1.6
5-year default insurance, bp End-2025 (pale) vs October 2026. Red: times higher What it is. A credit default swap pays out if the government defaults. The price is a yearly fee: 96bp is $9,600 a year to insure $1 million of French bonds.
Since 2021, bp Monthly close The 2011-12 crisis. On monthly closes, Italy’s cost peaked at 554bp and Spain’s at 590bp, in May 2012. CNBC says France’s is now the highest since that crisis.
2022 2023 2024 2025 2026 France 96 Italy 73 Spain 33 Germany 12
SourcesInvesting.com, 5-year CDS in US dollars, monthly closes to 22 Oct; CNBC 23 Oct
Amar Harolikar · Decision Sciences & Applied AI5 of 9tigzig.com
Slide 6
France’s debt is at a record. Italy, Greece, Spain and Portugal are below their 2020 peaks
France has had a deficit in all 31 years of Eurostat’s data, since 1995. Its interest bill nearly doubled in four years.
The refinancing wall. More than $1 trillion of French debt matures by 2030. France’s 10-year yield averaged 0.4% from 2015 to 2021. It is now 5.0%. Across all its debt, the interest paid in 2025 came to about 1.9%.
Debt, % of GDP 2025. France is third Greece 145% Italy 137% France 116% Belgium 108% Spain 101% Portugal 89% Germany 63% France’s deficit Within 3% in 8 of 31 years 1995 2010 2025 Interest paid, €bn France. €35bn in 2021 2015 2020 2025 66 France 116% in 2025, a record 2000 2010 2020 58% 116% Italy 137%, peak 155% in 2020 2000 2010 2020 155% 119% 137% Greece 145%, peak 209% in 2020 2000 2010 2020 209% 100% 145% Spain 101%, peak 119% in 2020 2000 2010 2020 119% 62% 101% Portugal 89%, peak 134% in 2020 2000 2010 2020 134% 62% 89% Belgium 108%, below 1995 2000 2010 2020 132% 108%
SourcesEurostat, ECB, CNBC 23 Oct. Country charts: own scales
Amar Harolikar · Decision Sciences & Applied AI6 of 9tigzig.com
Slide 7
The ECB’s tools are a poor fit for France
“If there are serious contagion effects from a hypothetical French crisis to other countries where the fiscal policy is much more sustainable, the ECB would probably use its TPI to shield these other countries, not France.”
Holger Schmieding, chief economist, Berenberg, to Reuters, 23 Oct
Deficit, % of GDP Dashed: the EU’s 3% cap 5.1% 2025 5.4% 2026 expected 5% 2027 budget
Gap over Germany bp. Italy at its euro-era worst month 168 France 23 Oct 519 Italy Nov 2011
The ECB’s two tools
Backstop The TPI buys bonds in a disorderly sell-off; never used. It needs EU fiscal rules followed and debt on a sustainable path; for France, ING says, at least a full budget passed.
Bailout The OMT is only for a government that first signs up to a bailout from the ESM, the euro rescue fund.
What to watch
27 Oct State budget debate resumes; MPs rejected the social security budget on 23 Oct. Using Article 49.3 invites a no-confidence vote.
29 Oct ECB meets. Seen on hold at 2.5%, with a rise expected in December.
5 Nov A national day of strikes and protests, backed by the unions.
Ratings Moody’s Aa3 (negative outlook) assumes a deficit-cutting budget and calmer borrowing costs and protests. BBB from all three after the election could force sales (RBC BlueBay).
13 Nov S&P reviews Italy (BBB+, positive outlook); an upgrade cuts the gap to two notches.
2027 Presidential election, 18 Apr and 2 May. Polls suggest the far right could win.
SourcesReuters 23 Oct, 23 Oct, Euronews, CNBC, Il Sole, Anadolu, Eurostat, ECB
Amar Harolikar · Decision Sciences & Applied AI7 of 9tigzig.com
Slide 8
The other side: most analysts see the contagion risk as limited, and banks are stronger than in 2011-12
Contagion CNBC, 23 Oct Most analysts CNBC spoke to said reforms keep the contagion risk limited this time, even though markets are behaving much as they did after the financial crisis.
Moody’s 23 Oct Kept Aa3 with a negative outlook, a notch above S&P and Fitch. It assumes a deficit-cutting budget and calmer borrowing costs and protests.
ING Carsten Brzeski “There is no risk of an imminent liquidity issue for the French government”, though the loss of bond-market trust should bring “a high sense of urgency to Paris”.
Citi Giada Giani, economist “There exists a consensus that Europe is better equipped today to deal with crises.” Re-emerging euroscepticism is a constraint, she adds.
BlackRock strategists The setting is “materially different” from 2011-12, though spillovers remain possible.
Banks Axiom, WisdomTree, via Reuters 21 Oct Better prepared. Large French banks’ home-government bonds are 15-30% of top capital, against 100%+ for Italy’s banks in 2011-12.
Interest Eurostat, 2025 France paid 2.2% of GDP, Italy 3.8%. France’s bill is rising.
SourcesReuters 23 Oct, CNBC 23 Oct, Reuters 22 Oct, Reuters 21 Oct, Eurostat
Amar Harolikar · Decision Sciences & Applied AI8 of 9tigzig.com
Slide 9
My read: France’s debt stress comes at a fragile time
In normal times, a debt scare in France would draw plenty of attention and noise, and something would get worked out. It would be a shock, but not one that puts the global economy at risk.
This time it comes on top of other stresses: AI valuations that look stretched and are increasingly funded with debt, an oil shock from the Iran war, and strain on jobs and incomes. With that much already stretched, a small trigger could have a far more destabilising effect.
My earlier analysis More at tigzig.com ➜ Analysis
24 OctCould this time be different? Past drawdowns, AI valuations, and cracks across markets and the economy.
23 OctA crescendo of warnings on AI debt and returns S&P Global, Gartner, Morgan Stanley, the IMF and the World Bank, in one month.
22 OctUS housing, October 2026 Mortgage rates above 2007-08, pending sales at a record low.
4 OctUS jobs, September 2026 Fewer new jobs, longer searches, hourly pay trailing prices since April.
31 AugA correction in AI valuations is looking more likely That view now comes from a central bank, an asset manager and a bond investor.
Not investment advice. This is my analysis of public sources, for information only. Care has been taken, but errors are possible. Use of AI. Parts of this work were prepared with AI under my direction. I reviewed, edited and approved every page. The analysis and conclusions are mine.
Amar Harolikar · Decision Sciences & Applied AI9 of 9tigzig.com
Working on something similar? How I work covers the rates, the availability and what I take on.