A Bond Shock Could Spread Faster: Hedge Funds Hold a Near-Record Share of Treasuries, Much of It on Borrowed Money
Published: October 18, 2026
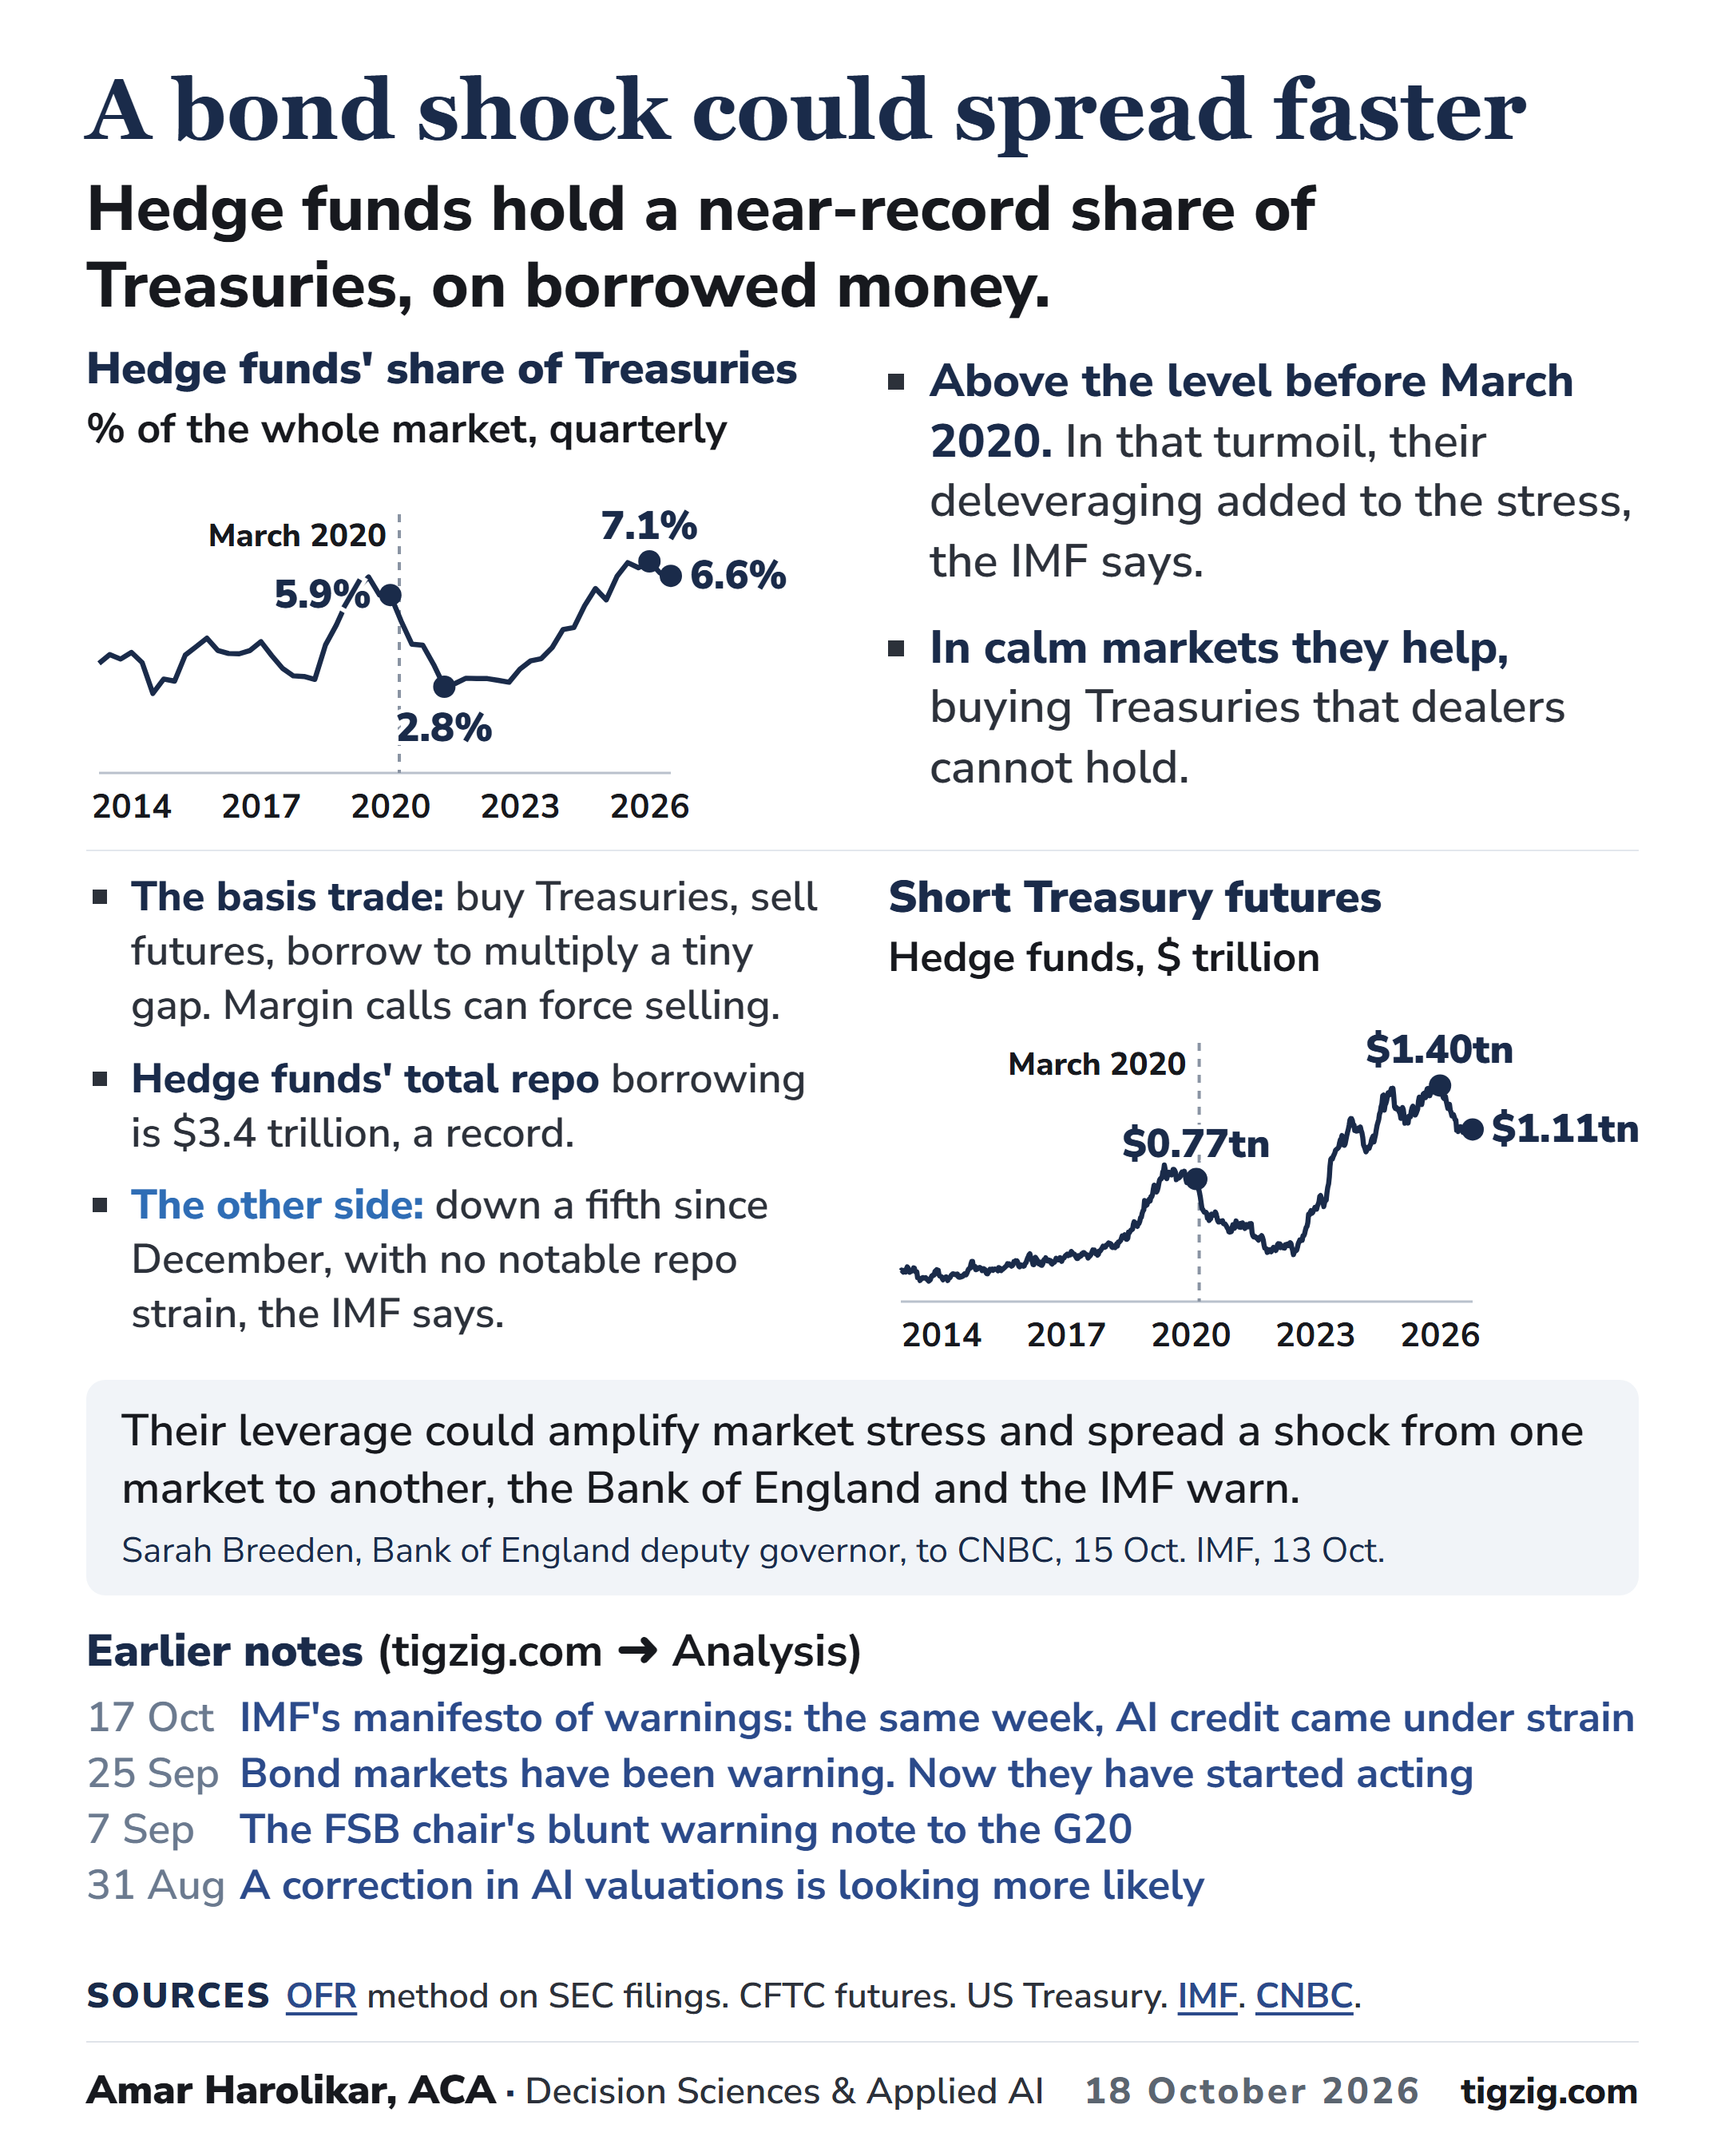
Hedge funds held 6.6% of US Treasuries in June, the latest data, near their record and much of it on borrowed money. The Bank of England and the IMF warned this week this makes a shock more likely to spread across markets.
That is up from 5.9% just before the March 2020 turmoil, and a good part of it is in the basis trade. A fund buys Treasuries, sells the matching futures and borrows to multiply the small price gap between the two, often 20 times or more according to Agecroft Partners.
Hedge funds' total repo borrowing, the short-term loans that fund trades like this and others, is a record 3.4 trillion dollars.
In calm markets this helps, because hedge funds buy Treasuries that the big dealers no longer have room to hold. In a selloff, margin calls can force them to sell fast, and the IMF says their deleveraging added to the stress in the March 2020 Treasury turmoil.
There is another side. The trade has come down about a fifth since December, going by hedge funds' short Treasury futures, most of it in the first half. The IMF says the unwind has caused no notable strain in repo markets, but the leverage still in these trades leaves the bond market open to a disorderly unwind.
This ties into what I have been tracking all year. The US 10-year closed above 5% in September for the first time since 2007, and this month it hit its highest since 2002. The FSB chair has warned the G20 of a potentially disorderly correction, and AI valuations look stretched (tigzig.com/analysis).
My sense is that leverage in the bond market is one way a shock in one market could reach the others.
The June share is my estimate using the OFR's method on SEC and CFTC data. Other sources are the US Treasury, the IMF and CNBC. The one-pager is below.
My earlier notes on this
IMF's warnings, 17 Oct. In the week the IMF warned about AI, bond yields and cyber attacks, AI credit came under strain: tigzig.com/post/imf-warnings-ai-credit-strain-oct2026
The bond market rout, 25 Sep. The US 10-year closed above 5% for the first time since 2007: tigzig.com/post/bond-market-rout-sep2026
Andrew Bailey, who chairs the Financial Stability Board, warned the G20 that markets remain vulnerable to a potentially disorderly correction that could spread across borders, 7 Sep: tigzig.com/post/fsb-chair-bailey-warning-sep2026
Bond markets are sounding an alarm, 6 Sep. The US 30-year was at 5.25%, and long rates were rising while the Fed was still cutting: tigzig.com/post/bond-markets-alarm-sep2026
A correction in AI valuations is looking more likely, 31 Aug: tigzig.com/post/ai-valuation-correction-aug2026
More analysis at tigzig.com/analysis
Working on something similar? How I work covers the rates, the availability and what I take on.